For buyers comparing homes in established St. Louis County neighborhoods, the decision often comes down to whether a property is ready for daily life or ready for a project. Sunset Hills real estate experts Patton Properties combines residential brokerage with custom-home, remodeling, investment-property, appraisal, and design-build experience. Patton Properties serves Sunset Hills and surrounding Missouri and Illinois communities, giving buyers a useful perspective on both neighborhood value and the practical scope of a renovation.
In Sunset Hills, a well-kept home with current finishes may offer a smoother transition, while an older home with solid fundamentals may offer an opportunity to tailor the space to your needs. Neither path is automatically better. The strongest decision starts with an honest all-in comparison.
What Separates a Move-In-Ready Home From a Fixer-Upper?
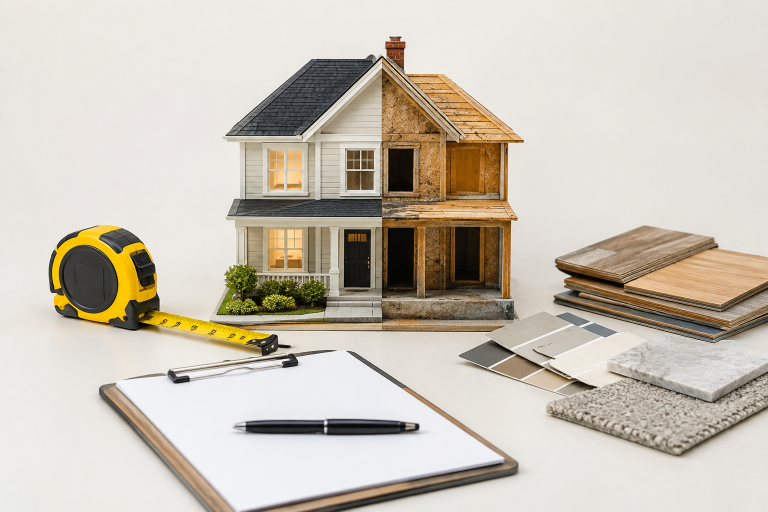
“Move-in-ready” generally means a buyer can occupy the home without major repairs. It does not guarantee that every system is new or that future maintenance will be unnecessary. A fixer-upper needs noticeable work before closing, soon after closing, or over time. The important distinction is whether the work is primarily cosmetic or involves safety, water control, structure, or major systems.
- Move-in-ready: Functional systems, current condition, and few immediate projects.
- Cosmetic fixer: Dated paint, flooring, fixtures, or cabinetry, but usable core systems.
- Major fixer: Possible roof, plumbing, electrical, drainage, structural, or foundation work.
- Full renovation: A project likely involving design decisions, permits, contractors, and extended scheduling.
What Current Market Research Shows
National conditions illustrate why conditions matter. A 2026 analysis of housing data found that fixer-uppers sold for about 7.3% less than comparable homes, while remodeled homes could command a premium of up to 3.7%. Those figures are not a substitute for a Sunset Hills pricing review, but they show that many buyers value certainty and completed improvements. Fixer-upper and move-in-ready market research also emphasizes the differences in time, maintenance, and planning between the two choices.
How To Compare the Full Cost
The listing price is only the starting point. For a home needing work, calculate:
Total Project Cost = Purchase Price + Closing Costs + Repairs + Professional Fees + Temporary Costs + Contingency Reserve
- General and specialist inspections
- Roofing, HVAC, plumbing, sewer, electrical, and drainage work
- Permits, design services, labor, materials, and appliances
- Insurance, utilities, taxes, storage, and temporary housing when needed
- Extra funds for concealed water damage, outdated wiring, or other discoveries
Do not devote every available dollar to the down payment and planned upgrades. A reserve gives you room to respond when an inspection or demolition reveals a problem that was not visible during the showing.
Which Repairs Deserve the Most Attention?
Prioritize safety and building performance before finishes. A beautiful kitchen does not solve a leaking roof, poor drainage, damaged framing, or unsafe electrical equipment. Attend the inspection when possible, ask questions, and obtain specialist opinions when the report identifies a serious concern.
- Foundation, framing, and signs of structural movement
- Roof condition and active water intrusion
- Electrical panels, wiring, and fire-safety concerns
- Plumbing supply lines, sewer connections, and water pressure
- Heating, cooling, ventilation, grading, and moisture control
- Windows, insulation, flooring, paint, kitchens, and bathrooms
Financing Options To Review
A standard mortgage may work for a home that meets lender condition requirements, while other financing may be better suited to a larger project. For example, FHA’s 203(k) rehabilitation mortgage program can combine the purchase or refinance of an eligible property with rehabilitation financing. Program rules, contractor requirements, draw schedules, and appraisal methods vary, so buyers should discuss current options directly with a licensed lender.
Questions To Ask a Lender
- Can renovation funds be included in the loan?
- Which repairs must be finished before closing?
- How are contractor payments released?
- How much cash must remain in reserve?
Lifestyle Factors Can Change the Answer
A move-in-ready home may fit buyers with a firm move date, limited repair experience, demanding work schedules, or a preference for predictable expenses. A fixer-upper may suit buyers with flexible timing, a dependable reserve, a clear design vision, and patience for contractor coordination. In either case, consider how the home will affect weekends, commuting, family routines, and stress levels.
A Simple Decision Framework
- Set an all-in budget, not just a maximum offer price.
- Separate essential repairs from preferred upgrades.
- Seek written estimates for major systems and structural work.
- Compare the completed cost with similar finished homes nearby.
- Add time for permits, materials, inspections, and scheduling changes.
- Choose the option that still feels manageable if costs or timing change.
Common Questions From Buyers
Is a fixer-upper always cheaper?
No. The purchase price may be lower, but repairs, financing, temporary housing, and delays can make the final cost higher than a finished home.
Should an old roof end the deal?
Not automatically. Review its remaining life, replacement estimate, insurance implications, and any signs of active leakage before deciding.
Can a first-time buyer handle a major renovation?
It is possible, but it requires realistic financing, qualified professionals, sufficient reserves, and a timeline that allows for setbacks.
Final Thoughts
A move-in-ready Sunset Hills home can offer comfort and predictability. A fixer-upper can offer location, customization, and a potentially lower entry price. Compare the overall financial picture, the home’s condition, and your capacity for the project before making an offer.